

MoneyPilot : Class Action
4.6

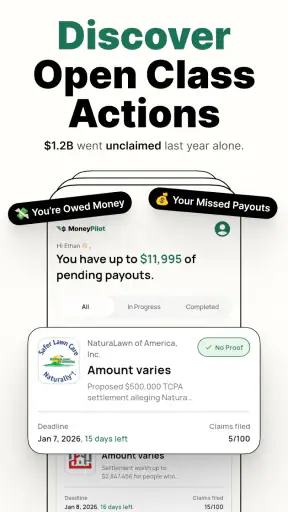
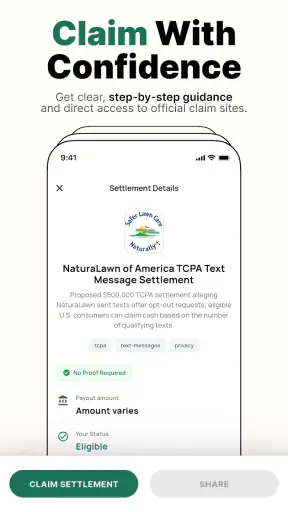
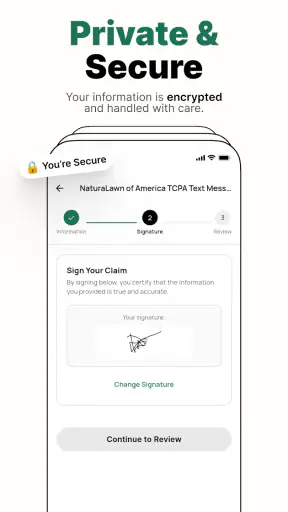
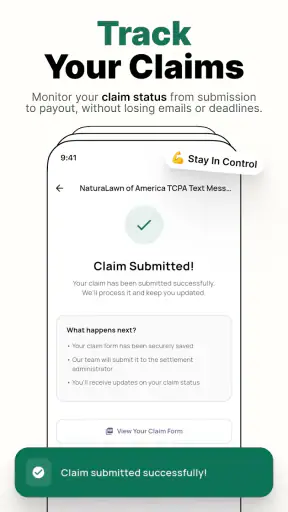
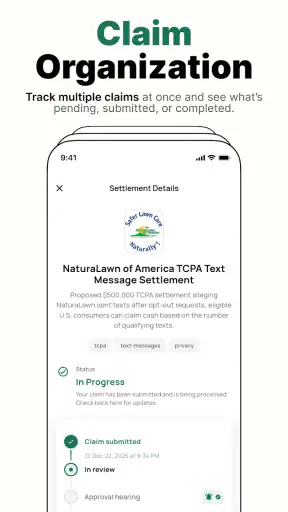
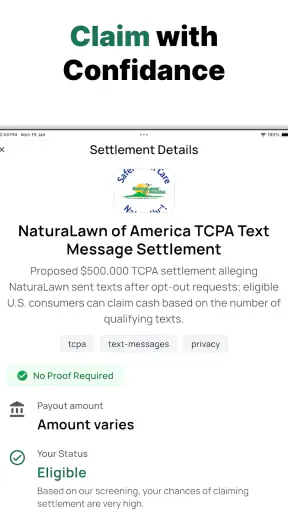
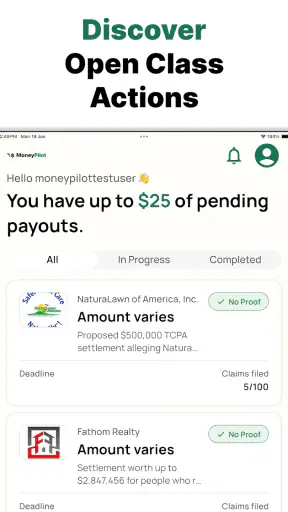
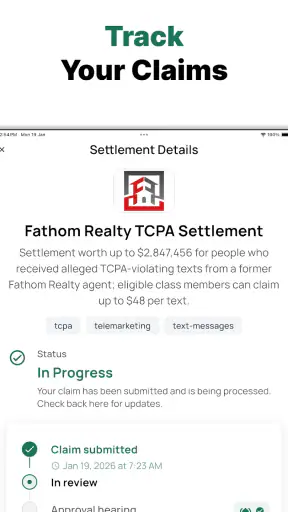
When I first opened MoneyPilot: Class Action, I approached it with a very practical question: could it help me find money I might otherwise overlook, or would it simply add another layer of paperwork to an already busy day? That is the right way to look at this finance app. It is designed around finding and tracking claims, submitting payout claims, and locating money connected with settlements. It is not a budgeting tool, investment platform, or replacement for a bank account. Its value depends on whether you have the patience to follow a claim from discovery through submission and then keep an eye on what happens afterward.
The app is developed by Bloom Processing and is free to install, with optional in-app purchases ranging from $3.99 to $99.99 per item. It is rated for Everyone, runs on Android 7.0 and later, and its current version is 1.0.55. The public response is encouraging, with a 4.6 average from around 1.9 thousand ratings and more than 50 thousand installs. Those figures suggest that the idea is attracting real interest, but they do not remove the need to read each claim carefully before handing over personal information or expecting a payout.
From an overlooked claim to a completed submission
Starting with the problem most people have
The starting condition is familiar: I may have heard about a settlement, seen a notice in an email, or simply wondered whether I qualify for money connected to a legal case. Usually, the difficult part is not deciding that a claim is worth checking. The difficult part is finding the relevant case, understanding the eligibility wording, locating the deadline, and remembering what I did afterward.
That is where MoneyPilot has a more focused purpose than ordinary finance apps. A banking app can show balances and transactions, while a spreadsheet can record deadlines once I already know them. Neither one is naturally built around the path from a possible settlement to a submitted claim. MoneyPilot puts that path at the center, which makes it more useful for people who regularly ignore notices because the process feels confusing or time-consuming.
I would not treat the app as a promise that every search will produce money. The sensible mindset is to use it as an organizer and discovery aid. A claim still has its own rules, evidence requirements, eligibility dates, and official administrator. The app can make the process easier to manage, but I still need to verify that the information I enter is accurate and that the claim genuinely applies to me.
Searching before deciding
The first useful habit is to search with realistic expectations. Instead of assuming that a familiar company name automatically means eligibility, I would begin with the details that usually matter: whether I used the product or service, when I used it, where I lived at the relevant time, and whether I still have supporting records. This prevents the common mistake of treating every result as free money.
A practical example would be a person who receives a settlement notice after changing email addresses. They may remember the company but not the case name, or they may have deleted an old purchase confirmation. In that situation, MoneyPilot can serve as a central place to investigate the opportunity and track the next step. The important work is still matching personal history to the claim requirements, rather than submitting the same information everywhere.
One of the app’s less obvious strengths is the way it encourages a separation between discovery and commitment. I can first identify a possible claim, then gather the relevant details before submitting anything. That is a better workflow than rushing through a form immediately, especially when a claim asks for dates, account information, proof of purchase, or a claim identifier.
Turning a possible match into an actionable task
Once I find a claim that appears relevant, I would pause and make a small checklist outside the excitement of the search. I would note the case or settlement name, the deadline, the required documentation, and the method by which a payment may eventually arrive. I would also record whether the claim allows one submission per person or household, because duplicate submissions can create confusion or invalidate an otherwise legitimate request.
This is where a tracking function becomes more valuable than a simple search screen. A discovery tool helps only once. A tracker can become a personal record of what I found, what I submitted, and what still needs attention. For someone managing several notices at once, that distinction matters. The real benefit is not merely seeing a list of opportunities; it is reducing the chance that an important deadline disappears in an inbox.
I also found that the best use of the app is deliberate rather than constant. I would set aside one short session to review possible claims, another to collect evidence, and a final session to check the submitted status. This three-stage approach avoids mixing incomplete searches with final submissions and makes it easier to notice when information has changed.
Submitting without losing control of the process
When I reach the submission stage, accuracy matters more than speed. A payout claim may ask for information that is easy to mistype, such as an address, account reference, or confirmation detail. I would compare every field with the original document before sending it. If the app allows me to review the claim before completion, I would treat that screen as a mandatory checkpoint rather than tapping through it automatically.
The most useful mental model is that MoneyPilot is a handoff point, not the final authority on eligibility or payment. It may help me find and submit a claim, but the settlement administrator is the party that evaluates the claim under the case rules. That means a submitted claim is not the same thing as an approved claim, and an approved claim is not necessarily an immediate payment.
This distinction answers one of the most important questions a new user may have: will installing the app guarantee a payout? No responsible workflow should assume that. The result depends on the claim, the user’s eligibility, the completeness of the submission, and the administrator’s process. I see the app as a way to improve organization and access, not as a shortcut around those conditions.
The handoffs after submission
After submission, the process becomes less active but not completely finished. The handoff may involve confirmation details, follow-up requests, and eventual communication from the administrator or another party handling the settlement. I would save confirmation information immediately and avoid relying on memory. If the tracker records the claim status, I would use it as a reminder system while keeping any official confirmation messages as the primary reference.
This is another area where the app can be more useful than a browser search. A search result disappears into browsing history, while a tracked item gives me a reason to return to it. That is especially helpful when the payment timeline is not immediate. The app’s role is to keep the claim visible until there is a clear outcome, whether that outcome is payment, rejection, a request for more information, or closure.
Still, I would not assume that every update will appear at the exact moment I want it. Users should remain alert to official correspondence and review the claim’s instructions directly. If there is a disagreement between an app status and an official notice, I would follow the official notice and use the app as a supporting record rather than treating it as the final word.
What the result looks like in everyday use
Imagine I receive a message about a settlement on a weekday evening. I remember using the relevant service but cannot recall the precise dates. I open MoneyPilot, look for the claim, and compare its requirements with old emails and account records. Rather than submitting immediately, I mark the opportunity for follow-up, gather the missing information, and return when I can complete the form carefully.
The outcome in this scenario is not simply “money found.” A better result is a documented process: I know why I may qualify, I know what I submitted, I have retained the confirmation, and I have a clear place to check progress. If the claim is accepted, the app has helped me reach that stage with less confusion. If it is rejected, I can at least understand which opportunity I pursued instead of wondering whether I missed the deadline entirely.
That workflow is particularly helpful for people who are organized in some parts of their financial life but inconsistent with administrative tasks. I may track bills carefully yet lose settlement notices among promotional emails. I may also be comfortable using banking apps but dislike legal forms. MoneyPilot sits between those habits: it gives the task a finance-oriented home without pretending to replace the official legal process.
Where the flow breaks down
The first point of friction is eligibility. Settlement language can be technical, and a quick match does not necessarily answer every qualification question. If I am unsure whether my circumstances fit, I would read the claim instructions in full rather than relying on a simplified description. The app may reduce searching time, but it cannot remove the need for judgment.
The second weakness is the possibility of incomplete personal records. A claim can be easy to discover but difficult to prove. If I no longer have receipts, old account emails, or the relevant address history, the submission stage may take longer than expected. This is not a failure unique to MoneyPilot, but it affects how much value I get from it. The app is strongest when I already have enough information to act.
Privacy and trust also deserve careful attention. A claims-focused finance app may involve sensitive personal details, so I would read the relevant explanations before entering anything unnecessary. I would avoid uploading documents simply because a field feels optional or because I want to finish quickly. The convenience of centralizing claim work should never encourage careless sharing.
There is also a financial consideration. The app itself is free to install, but optional purchases are available. I would not pay for an upgrade or add-on merely because a claim sounds promising. Before spending anything, I would compare the cost with the likely value of the claim, understand what the purchase actually changes, and check whether I can complete the essential task without it. A small payment can be reasonable in some workflows, but it should not become a condition for making a careful decision.
People who want a complete personal-finance dashboard may find the app too narrow. It is not the right choice if my main goal is expense categorization, savings targets, investment monitoring, or bill automation. A banking app or established budgeting service will be better for those jobs. MoneyPilot makes more sense as a specialized companion for settlement discovery and tracking, not as the only finance app on my phone.
How it compares with ordinary alternatives
The usual alternative is searching the web, checking email, and keeping notes in a spreadsheet. That approach costs nothing beyond time and can work well for a single claim. Its weakness appears when several opportunities overlap or when I forget which form I completed. MoneyPilot’s advantage is the dedicated workflow: search, evaluate, submit, and track in one purpose-built place.
A second alternative is relying on a lawyer, consumer organization, or settlement notice directly. Those sources may be preferable when the claim is complicated, the amount is significant, or my eligibility is disputed. Professional guidance can provide context that an app cannot. In that situation, I would use MoneyPilot for organization while treating expert advice and official case documents as more important than convenience.
A third alternative is ignoring small claims because the effort seems disproportionate. That can be rational when the documentation is extensive or the terms are unclear. However, the app may make modest opportunities worth reviewing because it reduces the initial search and gives me a way to keep track of the task. The trade-off is that I still need to spend attention on each claim, and attention is not free even when the download is.
Who will get the most from it
I think MoneyPilot is best for people who receive many consumer notices, frequently change addresses or email accounts, or have a habit of postponing administrative tasks. It is also useful for someone who wants one place to distinguish possible claims from completed submissions. The tracking element matters most for users who need reminders and a visible record rather than a one-time search.
I would be more cautious recommending it to someone who expects guaranteed payouts, instant results, or fully automatic eligibility decisions. It is also a poor fit for a user uncomfortable reviewing legal terms or verifying personal information. In those cases, a direct official source or professional assistance may be safer and clearer, even if the process feels less convenient.
Before installing, I would decide what I expect the app to do. If the goal is to investigate a settlement and manage the steps responsibly, it has a clear purpose. If the goal is general money management, the narrow focus will probably feel limiting. Knowing that difference prevents disappointment and keeps the app in the role where it is most useful.
My final assessment
After following the full path from a possible claim to a tracked submission, I see MoneyPilot as a practical organizer with a specific job. Its strongest contribution is not flashy finance automation; it is helping turn scattered settlement information into a sequence I can actually follow. The combination of discovery, payout-claim submission, and tracking gives it a clearer purpose than a generic notes app or a casual web search.
At the same time, I would use it with patience. I would verify eligibility, protect sensitive information, save confirmations, and keep official correspondence alongside the in-app record. I would also think carefully before buying any optional item, since a free installation does not mean every part of the experience must be treated as automatically worthwhile.
For me, the recommendation is straightforward: MoneyPilot is worth trying when settlement claims are the financial task you keep postponing. It can reduce the organizational friction between hearing about a claim and knowing what happened to it. It is not a substitute for reading the rules, proving eligibility, or waiting for an administrator’s decision, but as a focused claims companion from Bloom Processing, it offers a useful and reasonably approachable workflow. The app’s 4.6 average and growing audience make it interesting to explore, while its limitations are a reminder to stay involved at every handoff.
4.6
203.00 Reviews
Pros
- Tracks eligible class actions in one convenient place.
- Clear case summaries make complex legal details easier to understand.
- Helps users discover settlements they might otherwise miss.
- Useful deadline reminders can support timely claim submissions.
- Simple interface is accessible for users with limited legal knowledge.
Cons
- Eligibility criteria can vary widely between cases.
- Settlement payments may take months or longer to arrive.
- Some claims require detailed records or supporting documents.
- Available cases may depend on your location and personal history.
- The app cannot guarantee approval or the amount of any payout.


